
 Kontakt
 Wie einkaufen

Versand
Kaufberater
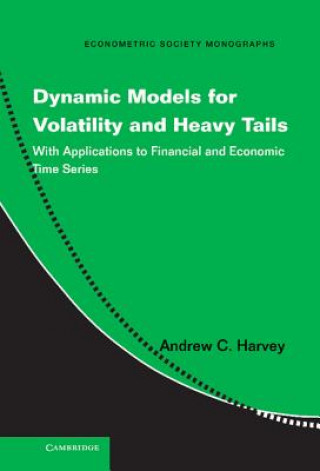
Dynamic Models for Volatility and Heavy Tails
With Applications to Financial and Economic Time Series
 Englisch
 326 b
Bis zu 30 Tage Rückgaberecht
Kunden kauften auch








The volatility of financial returns changes over time and, for the last thirty years, Generalized Autoregressive Conditional Heteroscedasticity (GARCH) models have provided the principal means of analyzing, modeling and monitoring such changes. Taking into account that financial returns typically exhibit heavy tails – that is, extreme values can occur from time to time – Andrew Harvey's new book shows how a small but radical change in the way GARCH models are formulated leads to a resolution of many of the theoretical problems inherent in the statistical theory. The approach can also be applied to other aspects of volatility. The more general class of Dynamic Conditional Score models extends to robust modeling of outliers in the levels of time series and to the treatment of time-varying relationships. The statistical theory draws on basic principles of maximum likelihood estimation and, by doing so, leads to an elegant and unified treatment of nonlinear time-series modeling.


Informationen zum Buch
Englisch

Verschenken Sie dieses Buch noch heute
Es ist ganz einfach
1 Legen Sie das Buch in Ihren Warenkorb und wählen Sie den Versand als Geschenk 2 Wir schicken Ihnen umgehend einen Gutschein 3 Das Buch wird an die Adresse des beschenkten Empfängers geliefertDas könnte Sie auch interessieren


 /
 Broschur
 16.09
€


 /
Broschur
31.99
€
 /
Broschur
10.29
€



Hallo! Ich bin Libroamiko, dein Buchberater.
Wie kann ich dir helfen?